Are you cruising the highways of Massachusetts and wondering what it might cost to insure your ride? Strap in, because we’re diving deep into everything you need to know about auto insurance in the Bay State.
From understanding the basic requirements to discovering the best ways to save on your premiums, this guide is here to help you navigate the often-confusing world of auto insurance. Let’s hit the road!
Overview of Auto Insurance in Massachusetts
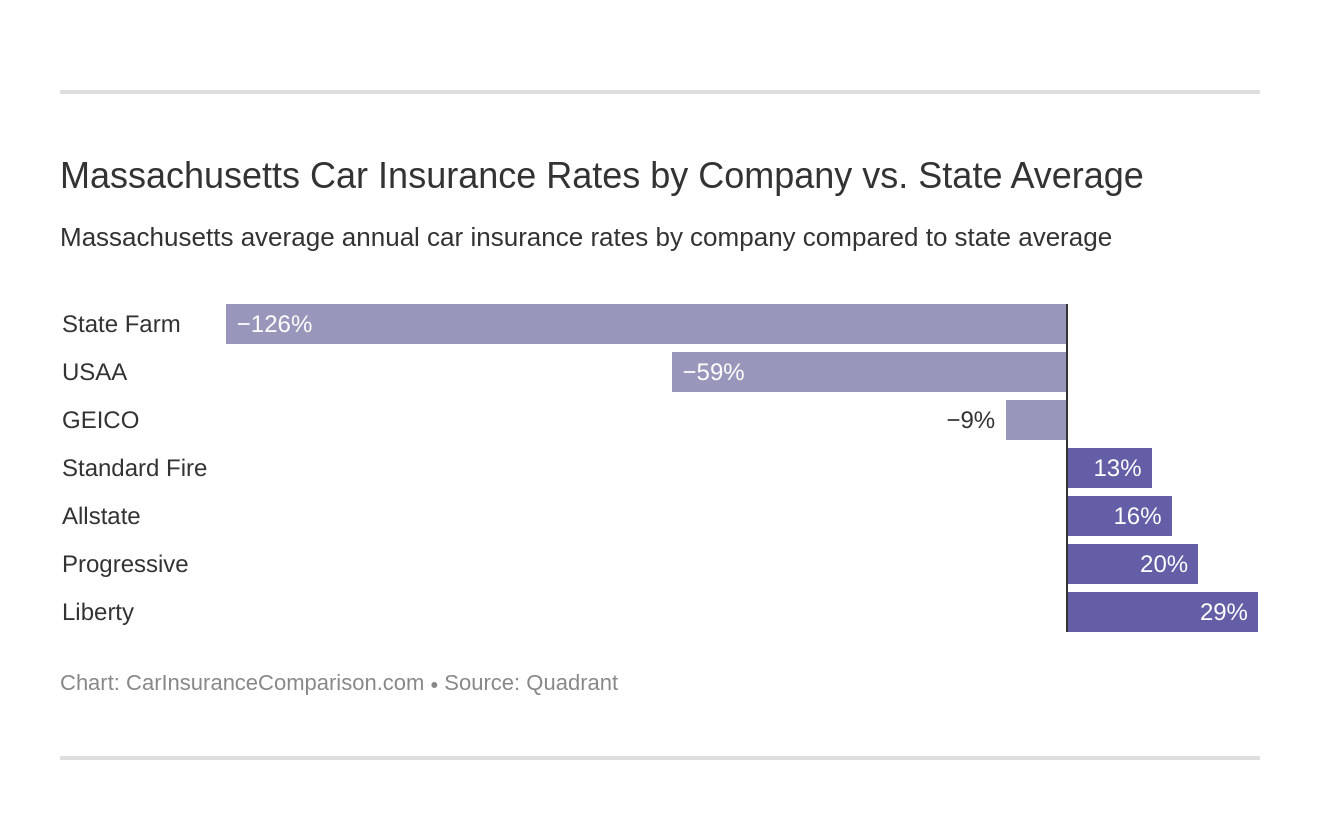
Did you know that Massachusetts has some of the strictest auto insurance requirements in the U.S.? If you’re driving in the Bay State, you better be insured, or you’re in for a hefty fine. Let’s break down what you need to know.
Massachusetts mandates that every driver carries a minimum level of auto insurance. This includes liability coverage for both bodily injury and property damage. Without these, you can’t legally drive. BUT there’s more to consider beyond the basics.
The Types of Coverage Available
Massachusetts offers a variety of auto insurance options. Beyond the mandatory liability coverage, you can opt for collision coverage to cover repairs to your vehicle in an accident. There’s also comprehensive coverage to handle damages from non-collision events like theft or natural disasters.
For those looking at extra protection, Personal Injury Protection (PIP) covers medical expenses and lost wages, regardless of who caused the accident. And if you’re worried about uninsured drivers, there’s coverage for that too.
Factors Influencing Auto Insurance Premiums
Why do your insurance rates seem higher than your friend’s? A few key factors come into play. First, your driving record is a biggie. Tickets or accidents? You can bet your rates will climb.
Then there’s the type of car you drive. Luxury cars mean luxury premiums. Location matters too. Living in a high-traffic area? Expect to pay more.
Here’s the deal: by understanding these factors, you can strategically lower your costs.
Pro Tip: Compare multiple insurance quotes annually to ensure you’re getting the best rate possible. Rates can fluctuate, and a little research can save you big bucks!
Average Costs of Auto Insurance
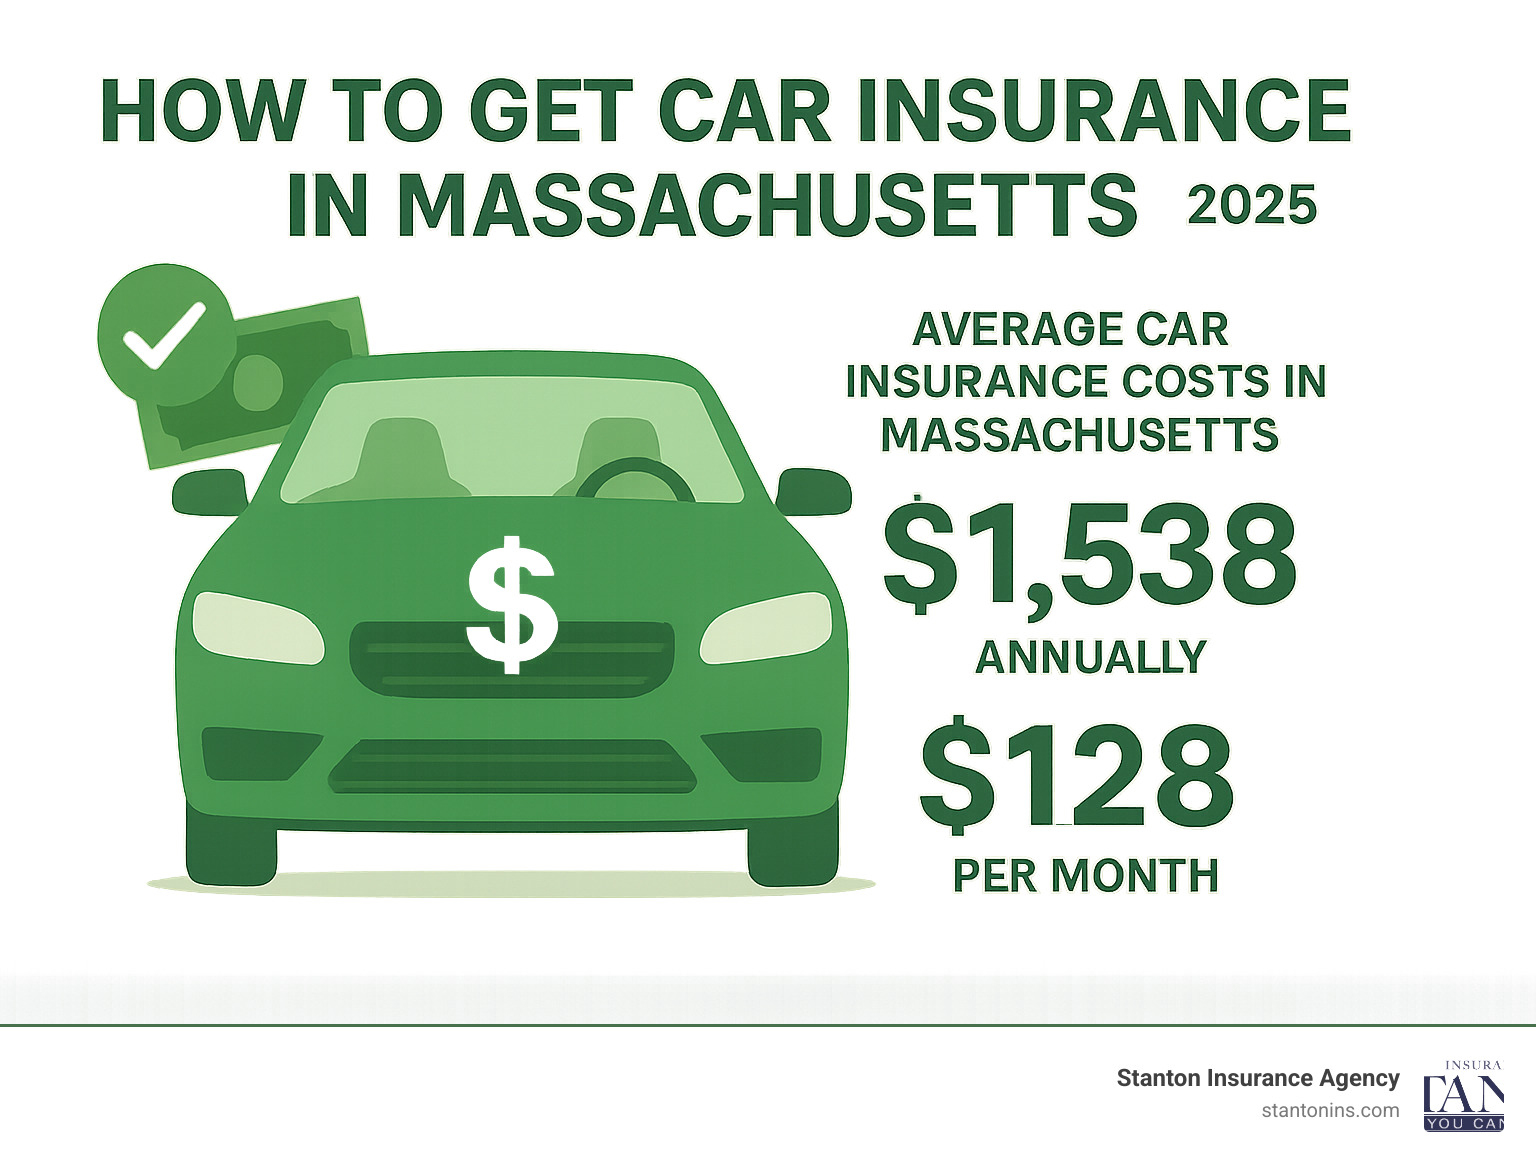
Did you know that auto insurance in Massachusetts isn’t as expensive as you might think? Surprisingly, it’s cheaper than many other places in the country. But, there are key factors that can make your costs go up or down.
On average, Massachusetts drivers pay around $1,200 annually for their auto insurance. That’s way lower than states like New York and Michigan, where costs can skyrocket to over $2,000. But, it pays to know what influences these rates.
Factors That Influence Auto Insurance Costs
Your driving record, age, and even your credit score can dramatically change what you pay. Young drivers typically pay more. If you have a clean driving record, expect a discount. But, if you live in a city like Boston, get ready to fork out more due to higher accident rates.
Pro Tip: Always shop around and compare quotes from different insurers to snag the best deal!
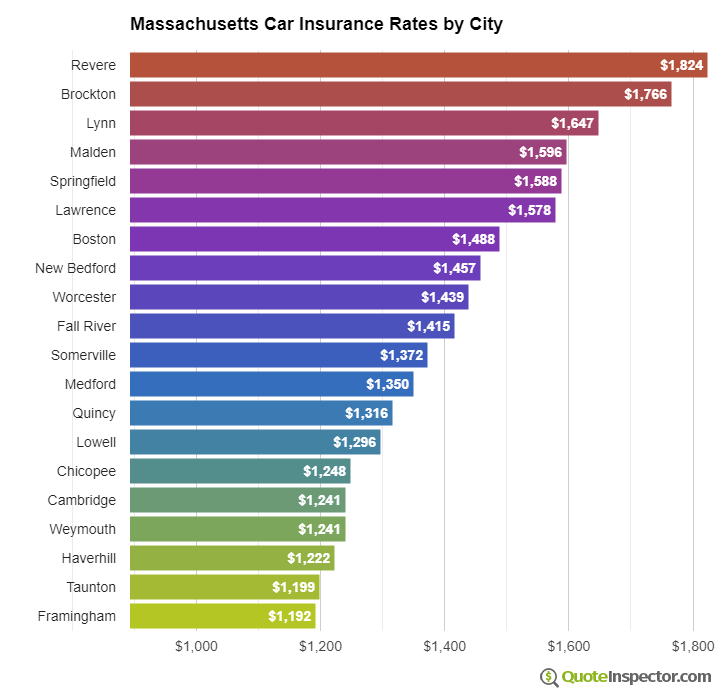
Comparing Costs Across Massachusetts Cities
Here’s a quick look at how auto insurance costs stack up in different cities within Massachusetts:
| City | Average Annual Cost |
|---|---|
| Boston | $1,500 |
| Worcester | $1,250 |
| Springfield | $1,200 |
| Cambridge | $1,300 |
| Lowell | $1,100 |
Factors Affecting Auto Insurance Rates
Did you know that two drivers with the same car can pay drastically different insurance rates in Massachusetts? It’s all about the details that define you and your ride.
Insurance companies use a cocktail of factors to determine how much you shell out. Let’s break down these elements to see how they impact your wallet.
Driving History Impacts Auto Insurance Rates
Your driving record is like a financial report card. If you’ve got a clean slate, you’re golden. But if your history is littered with speeding tickets or accidents, brace yourself for higher premiums. Insurers see past offenses as red flags, translating into a greater risk. And you know what that means: higher costs for you.
The Role of Vehicle Type and Age on Insurance Costs
The car you drive plays a significant role in determining your insurance rate. Flashy, expensive rides are costly to insure. Why? Repair and replacement costs skyrocket if you crash a high-end vehicle. In contrast, older, low-value cars tend to have lower premiums. And if your vehicle is prone to theft, expect to pay even more.
Other Personal and Geographical Factors
Your ZIP code might be more significant than you think. City dwellers often face higher rates because of increased traffic and theft risks. Age matters too. Younger drivers typically pay more due to their inexperience. And if you’re married, you might catch a break—statistics show married folks file fewer claims.
Pro Tip: Boost your savings by bundling auto and home insurance. It’s like getting a combo meal at a discount.
Insurers dive deep into a mixture of personal and geographical factors to fine-tune your rate. Where you live, your age, and even your marital status all play a part in this complex equation.
Discounts and Ways to Save on Auto Insurance
Want to slash your auto insurance bill by up to 25%? It’s all about finding the right discounts and strategies to lower your premium.
Many drivers in Massachusetts are overpaying for their auto insurance. The good news? You don’t have to be one of them. By tapping into various discounts and adopting smart habits, you can keep more money in your pocket.
Methods to Qualify for Auto Insurance Discounts
Auto insurers in Massachusetts offer a variety of discounts. The key is knowing which ones you qualify for. For instance, if you have multiple cars or a home insurance policy with the same company, you might qualify for a multi-policy discount. And if you’re a safe driver with no accidents, you could score a good driver discount.
- Multi-policy discount
- Good driver discount
- Low mileage discount
- Student discount
- Safety device discount
Reduce Premiums Through Safe Driving and Strategies
Let’s break it down. Safe driving doesn’t just keep you safe—it also helps reduce your insurance premiums. Enroll in a defensive driving course and insurers might reward you with a discount. Keep a clean driving record, and your rates can drop even further.
Here is the deal: Some insurers provide usage-based insurance. They track your driving habits—mileage, speed, etc.—and offer discounts for responsible behavior. Plus, parking your car in a garage or adding safety features like anti-theft devices can also lower your rates.
Pro Tip: Combine multiple strategies for maximum savings on your insurance!
Comparing Insurance Providers
Did you know that choosing the right insurance provider could save you hundreds of dollars each year? It’s true! But with so many options, how do you pick the best one for your needs?
Let’s dive into the nitty-gritty of comparing the major auto insurance providers in Massachusetts. You’ll discover the differences in coverage options and customer satisfaction ratings. Plus, I’ll show you how to choose the best provider based on your unique needs.
Coverage Options and Customer Satisfaction
When it comes to coverage, not all insurance providers are created equal. Some offer more comprehensive options, while others might excel in customer service. Here is the deal: finding the right balance is crucial. Start by identifying what’s most important to you – is it cost, customer service, or perhaps specific coverage options?
Now, let’s look at how major providers stack up:
| Provider | Coverage Options | Rates | Customer Reviews |
|---|---|---|---|
| Provider A | Comprehensive, Collision, Liability | $$ | 4.5/5 |
| Provider B | Liability, Uninsured Motorist | $ | 4/5 |
| Provider C | Collision, Roadside Assistance | $$$ | 3.8/5 |
| Provider D | Comprehensive, Personal Injury | $$$ | 4.2/5 |
How to Choose the Best Provider
Here’s how you can choose the best provider for your needs. Step #1: Assess your personal situation. Do you drive a lot? Do you have a new car? Your needs can determine the type of coverage you should prioritize.
Step #2: Compare rates but don’t just go for the cheapest option. A lower rate might mean less coverage. Step #3: Read customer reviews. They offer real insights into what you can expect in terms of service.
Pro Tip: Always ask about discounts. Many providers offer them for good driving records, multiple policies, or even for being a loyal customer.
By following these steps, you’ll be better equipped to find an insurance provider that fits your needs and budget in Massachusetts. Remember, your needs should dictate your choice, not just the price tag on the policy. Happy hunting!
Legal Considerations and Requirements
Did you know that driving without insurance in Massachusetts could cost you up to $5,000 in fines? That’s right. Massachusetts takes auto insurance seriously, and so should you.
In Massachusetts, having auto insurance isn’t just a suggestion; it’s the law. This means you must meet certain coverage requirements to legally drive. Let’s break down what you need to know to stay on the right side of the law.
Auto Insurance Minimum Requirements
Massachusetts requires drivers to have a few types of insurance coverage. First, you need Bodily Injury to Others with a minimum of $20,000 per person and $40,000 per accident. You’re also required to have Personal Injury Protection (PIP) of $8,000 per person, which covers medical expenses regardless of fault. Then there’s Bodily Injury Caused by an Uninsured Auto with at least $20,000 per person and $40,000 per accident. Finally, don’t forget Damage to Someone Else’s Property at $5,000 minimum coverage.
Consequences of Inadequate Coverage
Driving without adequate insurance isn’t just risky—it’s costly. If you’re caught, you could face fines ranging from $500 to $5,000. That’s not all; your license and registration could be suspended, leaving you without legal access to the roads. And if you’re involved in an accident without coverage? Expect to face expensive out-of-pocket costs. Here’s the deal: skipping on insurance is a gamble you don’t want to take.
Filing an Auto Insurance Claim in Massachusetts
Getting into an accident is stressful enough without the added headache of a complicated claims process. But fear not—here’s how you can make it seamless. Step #1: Report the accident to your insurance company as soon as possible. Step #2: Provide all necessary documentation, such as police reports and photos. Finally, stay in contact with your claims adjuster to ensure everything is processed smoothly.
Pro Tip: Always keep a copy of your insurance policy and contact details in your car. This makes the claim filing process much easier!
Closure
Whether you’re a seasoned driver or just getting your license, understanding auto insurance in Massachusetts is crucial. Armed with this knowledge, you’re equipped to make smart decisions that keep both your wallet and your peace of mind intact. Drive safely and make those insurance decisions count!
FAQ Section
What are the basic requirements for auto insurance in Massachusetts?
In Massachusetts, drivers must carry a minimum amount of liability insurance, including Bodily Injury to Others, Personal Injury Protection (PIP), Bodily Injury Caused by an Uninsured Auto, and Damage to Someone Else’s Property.
How does my driving history affect my insurance rates?
Insurers look at your driving record to assess risk. A clean driving history usually results in lower premiums, while accidents and traffic violations can increase costs.
What factors influence the cost of auto insurance?
Factors include your age, driving history, vehicle type and age, location, and even your credit score. Each plays a role in determining your premium.
How can I save on auto insurance premiums in Massachusetts?
You can save by maintaining a clean driving record, choosing a car with a good safety rating, bundling policies, or looking for discounts offered by insurers.
What should I consider when choosing an insurance provider?
Look at coverage options, customer satisfaction, rates, and financial stability. Compare these aspects to find the provider that best meets your needs.
